TL;DR — Quick Summary
- Vertical specialization is the most significant competitive trend in payments that most ISOs are not responding to: Restaurant specialists, healthcare payment experts, and retail niche players are systematically taking market share from generalist ISOs by delivering deeper vertical expertise, higher merchant retention, and more relevant product development. The ISO that assumed breadth was a competitive advantage is discovering that depth beats breadth in every vertical where a specialist has established a presence. This is not a future trend — it is happening now, in restaurants, healthcare, retail, and beauty.
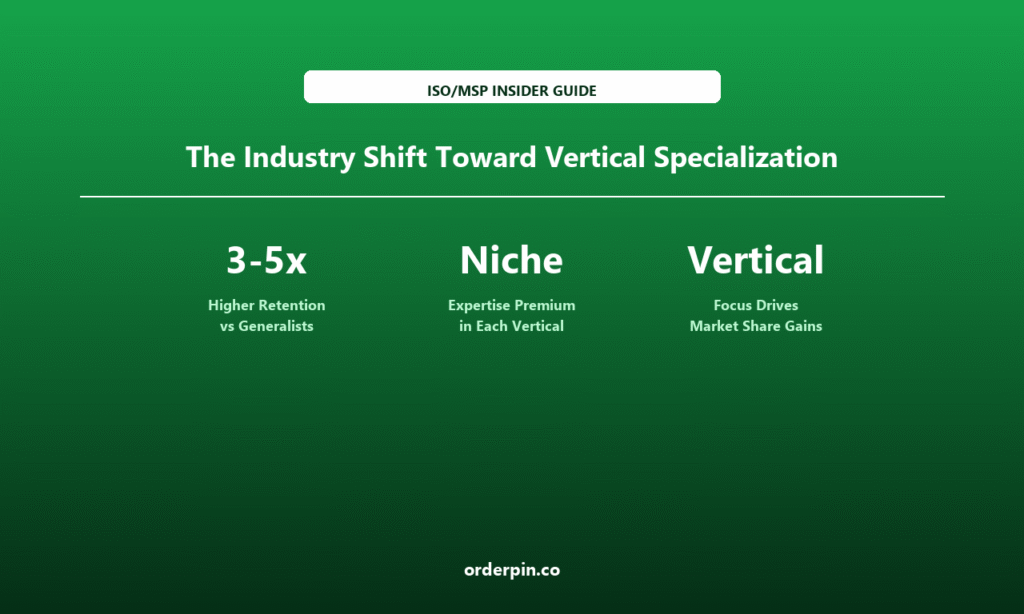
- Specialists outperform generalists on every metric that matters to merchants in their vertical: Merchant retention in specialist portfolios is 3-5x higher than in generalist portfolios because the specialist understands the merchant’s business — not just their payment volume. Product development in specialist companies is more relevant because every feature is built for one industry. Sales cycles are shorter because the specialist speaks the merchant’s language and understands their pain points. The generalist’s advantage — serving all verticals — becomes a disadvantage when the specialist is better at serving each one.
- The strategic question for every ISO is whether to specialize, to partner, or to accept the consequences of staying generalist: The ISO that chooses specialization commits to becoming the expert in a defined vertical, building deep product capabilities and domain knowledge that a generalist cannot replicate quickly. The ISO that chooses partnership works with vertical SaaS platforms that serve the specialist function, distributing their product through the platform while leveraging its vertical expertise. The ISO that does neither will face increasing pressure from specialists in every vertical they serve — with no structural advantage to respond with.
vs Generalists
in Each Vertical
Market Share Gains
The Quiet Shift Toward Vertical Specialization in Payments
The payments industry has always had generalists — ISOs that serve restaurants, retailers, service businesses, and e-commerce without specializing in any of them. For decades, this breadth was a competitive advantage: the generalist ISO could sell to any merchant, build volume across verticals, and avoid the concentration risk of depending on a single industry. That advantage is eroding. The rise of vertical SaaS, the growth of specialist payment providers, and the increasing sophistication of merchant expectations are making depth more valuable than breadth in every vertical where a specialist has established a presence.
The shift is quiet because it is happening gradually — a specialist here, a vertical focus there — but it is systematic. Restaurant payment specialists are taking restaurant accounts from generalists. Healthcare payment experts are building practices in medical and wellness verticals. Retail niche players are developing capabilities that generalist ISOs cannot match. The merchant that chooses a specialist over a generalist is making a rational decision: the specialist understands their business better, builds more relevant products, and retains them longer. The question for generalist ISOs is not whether specialization is a real trend — it is whether they want to be the specialist, the partner, or the displaced generalist.
This article maps the specialization trend across verticals, explains why specialists outperform generalists on merchant retention and revenue per merchant, and outlines the strategic options available to ISOs that are currently competing as generalists.
Generalist Portfolios
Segment Growth
Per Specialist Merchant
in Every Vertical
1. Why Specialists Outperform Generalists on Merchant Retention
Specialists understand the merchant’s business — not just their payment volume: A restaurant specialist knows what a busy Friday night looks like, what the average table turn time is, what the seasonal cash flow pattern is for a QSR versus a fine dining establishment. That knowledge translates into better product design, more relevant sales conversations, and more valuable advisory services. A generalist ISO serving the same restaurant knows their payment volume, their average ticket, and their seasonal variation — but not the operational context that makes the specialist’s advice genuinely useful.
Merchant retention in specialist portfolios is 3-5x higher because the switching cost is expertise, not just platform: The merchant that has built their operations around a specialist’s product — a restaurant POS designed for their service model, a healthcare payment system built for their patient flow — is not just switching a processor when they consider an alternative. They are switching the operational expertise embedded in the product. Generalist alternatives may offer competitive rates, but they cannot replicate the operational fit that the specialist has built over years of focused development. That depth of fit is the retention driver that generalists cannot match on rate alone.
2. The Verticals Where Specialization Is Already Winning
Restaurants: the most mature specialist vertical and the clearest proof of concept: Toast, Lightspeed, and Square for Restaurants have established specialist positions in restaurant payments that generalist ISOs cannot easily dislodge. These specialists understand the difference between a quick-service restaurant and a fine dining establishment, between a food truck and a ghost kitchen. Their product development is faster and more relevant because every feature request comes from restaurant operators. Generalist ISOs serving restaurants are increasingly competing on rate alone — which is a losing position against a specialist that offers operational fit.
Healthcare and wellness: the next frontier with the highest revenue per merchant: Medical practices, dental offices, and wellness clinics have payment complexities — insurance integration, payment plans, HSA/FSA processing, recurring billing — that generalist processors handle poorly. Healthcare payment specialists are building practices in this vertical by offering integrated solutions that generalists cannot match. The revenue per merchant in healthcare is significantly higher than in retail or restaurants, which makes this vertical particularly attractive for specialists — and particularly vulnerable for generalist ISOs that have healthcare merchant accounts without healthcare-specific capabilities.
Beauty, fitness, and service: the subscription and recurring revenue verticals: Salons, spas, and fitness studios operate on membership models that require recurring billing, automated reminders, and flexible payment scheduling. Generalist processors treat these merchants like any other service business. Specialists have built platforms around the subscription and recurring revenue model that generalists cannot easily replicate — with retention rates that reflect the operational depth of the specialist’s solution. The generalist that serves a salon without membership management capabilities is offering an incomplete solution.
3. Why the Generalist Position Is Becoming Less Defensible
Generalism is a competitive strategy that worked when specialists did not exist in every vertical: The generalist ISO’s advantage was always breadth — the ability to serve any vertical without specialization. That advantage required the absence of credible specialists in most verticals. As specialists have emerged in restaurants, healthcare, beauty, and retail, the generalist’s breadth advantage has eroded in each of those verticals. The generalist that served all verticals now faces specialists in each one — and is discovering that depth beats breadth when the specialist is credible.
The generalist’s product development disadvantage compounds over time: A specialist company building for one vertical allocates 100% of its product development resources to that vertical. A generalist ISO allocating development resources across restaurants, retail, healthcare, beauty, and e-commerce is spreading those resources thin. Over time, the specialist’s product becomes more relevant, more feature-rich, and more operationally integrated — while the generalist’s product falls further behind in every vertical it serves. The longer a generalist waits to specialize, the harder the catch-up becomes.
4. The Three Strategic Paths for the Generalist ISO
Path 1 — Choose a vertical and commit to becoming the specialist: The ISO that chooses specialization selects a vertical with high revenue potential, significant operational complexity, and limited credible specialist competition, and commits to building deep domain expertise, product capabilities, and market positioning in that vertical. This path requires investment — in product development, vertical-specific sales training, and domain expertise — but it creates a defensible position that a generalist cannot replicate quickly. The ISO that specializes in healthcare payments, for example, builds a moat that a restaurant-focused competitor cannot cross.
Path 2 — Partner with specialists rather than compete against them: The ISO that cannot or does not want to specialize can partner with vertical SaaS platforms that serve the specialist function — distributing their white-label POS through the platform, leveraging the platform’s vertical expertise while maintaining the distribution relationship. This path allows the ISO to participate in the specialist’s market position without building the specialization from scratch. It is a partnership, not a competition — and it requires finding the right vertical platforms to work with.
Path 3 — Accept competitive pressure and compete on service in remaining verticals: The ISO that chooses neither specialization nor partnership will face increasing pressure from specialists in every vertical they serve. In this scenario, the ISO’s only remaining competitive advantage is service depth — the customer success programs, relationship quality, and responsiveness that keep merchants loyal when product depth is not on their side. This path is viable in the short term but deteriorates over time as specialist products improve and merchant expectations rise.
5. The Competitive Imperative for Every Generalist ISO
The decision to specialize or partner is a strategic choice that must be made deliberately: Most generalist ISOs have not made a deliberate decision about specialization — they have simply continued operating as generalists because that is how they started. The specialization trend is not going to reverse. The verticals that are currently being captured by specialists will continue to be captured unless generalist ISOs make a deliberate strategic choice to compete differently. The ISO that makes this choice now — before the specialist has fully established their position in their target verticals — has a better chance of building a defensible specialization than the ISO that waits.
The white-label POS platform is the foundation of any specialization strategy: Whether the ISO chooses to specialize by building vertical-specific product capabilities or to partner with vertical SaaS platforms, platform ownership is the foundation. A white-label POS under the ISO’s brand gives the ISO the flexibility to build vertical-specific features, integrate with vertical-specific tools, and position themselves as the specialist in their chosen vertical — rather than reselling a generalist platform that cannot match the specialist’s depth. The platform is not just a product; it is the foundation of the ISO’s competitive positioning in any vertical they choose to serve.
Specialist vs Generalist ISO Performance
| Metric | Vertical Specialist | Generalist ISO |
|---|---|---|
| Merchant Retention Rate | 90%+ (specialist verticals) | 75-85% |
| Revenue Per Merchant | 30%+ premium (specialist segments) | Baseline |
| Product Relevance | Built for one vertical | One size fits all |
| Product Development | 100% focused on one vertical | Thin spread across verticals |
| Sales Cycle Length | Shorter (speaks merchant language) | Longer (generalist pitch) |
| Long-term Trajectory | Gaining share in verticals | Losing share in specialist verticals |
How OrderPin Helps ISOs Build a Defensible Vertical Specialization Strategy
OrderPin is a white-label POS platform that gives ISOs the platform foundation to build vertical specialization — whether the ISO is specializing in restaurants, healthcare, beauty, or any other vertical. A white-label POS under the ISO’s brand gives the ISO the flexibility to build vertical-specific features, integrate with vertical-specific tools, and position themselves as the expert in their chosen vertical — not a generalist reselling a one-size-fits-all product.
- Build vertical-specific product depth: OrderPin lets an ISO customize features, integrations, and workflows for their chosen vertical — building the operational depth that makes a specialist’s product genuinely better than a generalist’s for merchants in that vertical.
- Position as the vertical expert, not a generalist: A white-label POS under the ISO’s brand lets the ISO own the vertical positioning — the specialist narrative, the vertical-specific integrations, the domain expertise — that differentiates them from generalist competitors and from platform vendors that do not specialize.
- Partner with vertical SaaS platforms from a position of strength: The ISO that owns their white-label POS platform is a more attractive partner for vertical SaaS platforms than a generalist reseller — because the ISO controls their own product roadmap, their own data, and their own merchant relationships, not a vendor’s.
- Build the switching costs that protect specialist positioning: The ISO that owns their platform and builds vertical-specific depth creates switching costs — operational integration, custom workflows, vertical-specific data — that a generalist competitor cannot match on rate alone. The specialization compounds as the ISO’s vertical expertise deepens.
Frequently Asked Questions
Why is vertical specialization the most significant competitive trend in payments?
Because specialists outperform generalists on every metric that matters to merchants in their vertical: retention (3-5x higher), revenue per merchant (30%+ premium), product relevance, and sales cycle length. As specialists establish credible positions in restaurants, healthcare, beauty, and retail, generalist ISOs are discovering that breadth is no longer a competitive advantage when the specialist is better at serving each vertical. The shift is happening now, in every vertical where a credible specialist has emerged.
What verticals are specialists winning in right now?
Restaurants (Toast, Lightspeed, Square for Restaurants — the most mature specialist vertical), healthcare and wellness (medical, dental, and clinic payment specialists with integrated billing and HSA/FSA processing), and beauty/fitness (salon, spa, and fitness studios with membership and recurring billing). Healthcare has the highest revenue per merchant and the most operational complexity, making it the most attractive specialist target and the most vulnerable generalist gap.
How do specialists build higher merchant retention than generalists?
Through operational depth and domain expertise that makes the specialist’s product genuinely better fit for the merchant’s business — not just a better rate. A restaurant specialist understands the operational flow of a QSR versus fine dining; a healthcare specialist understands insurance integration, payment plans, and HSA processing. This depth translates into switching costs that are expertise-based, not just platform-based: the merchant that switches from a specialist loses the operational fit that the specialist built over years of focused development.
What are the three strategic paths for a generalist ISO?
Specialize: choose a vertical, commit to building domain expertise and product capabilities, and become the credible specialist. Partner: work with vertical SaaS platforms that serve the specialist function, distributing through the platform while leveraging its vertical expertise. Accept competitive pressure: compete on service depth in remaining verticals without specialization — viable short-term but deteriorating as specialist products improve.
How does platform ownership support vertical specialization?
A white-label POS under the ISO’s brand gives the ISO the flexibility to build vertical-specific features, integrate with vertical-specific tools, and own the specialist positioning in their chosen vertical — not a vendor’s. Platform ownership also gives the ISO the data, the merchant relationships, and the product roadmap control that make them an attractive partner for vertical SaaS platforms, and a credible competitor for specialist payment providers.
When does the generalist position become untenable?
When a credible specialist has established a position in every vertical the generalist serves. The generalist’s competitive advantage — breadth — requires the absence of credible specialists in most verticals. Once specialists have credible positions in restaurants, healthcare, beauty, and retail, the generalist is competing on rate alone in each of those verticals — which is a deteriorating position, not a sustainable one. The window to specialize is before the specialist has fully established their position, not after.
Vertical specialization is the most significant competitive trend in payments, and it is happening now — not as a future threat, but as an ongoing market shift that is taking share from generalist ISOs in restaurants, healthcare, beauty, and retail. Specialists outperform generalists on every metric: 3-5x higher merchant retention, 30%+ revenue premium per merchant, faster sales cycles, and more relevant product development. The generalist ISO that assumed breadth was a competitive advantage is discovering that depth beats breadth in every vertical where a specialist has established a credible position. The strategic choice is not whether to specialize — the specialization trend will not reverse — it is whether to become the specialist, to partner with specialists, or to accept the consequences of staying generalist. The white-label POS platform is the foundation of any specialization strategy: it gives the ISO the flexibility to build vertical-specific depth, own the specialist positioning, and create the switching costs that protect their vertical market share. OrderPin is a white-label POS platform that gives ISOs the foundation to build vertical specialization — owning the product, the data, and the merchant relationship in their chosen vertical, rather than reselling a generalist product that cannot match a specialist’s depth.
About OrderPin
OrderPin is a white-label POS platform built for ISO and MSP partners. We offer full data ownership, flexible pricing, and seamless API integrations to help you build a recurring revenue business under your own brand. Learn more about OrderPin’s white-label solution